Debt can get loud fast. It can start sounding like a personality description instead of a temporary problem. People say things like, “I am terrible with money,” or “I am just the kind of person who ends up in debt,” as if a credit card balance somehow rewrote their identity. But debt is not a secret identity hiding under your clothes. It is a situation. It may be stressful, complicated, or deeply unfair, but it is still a situation, which means it can change.
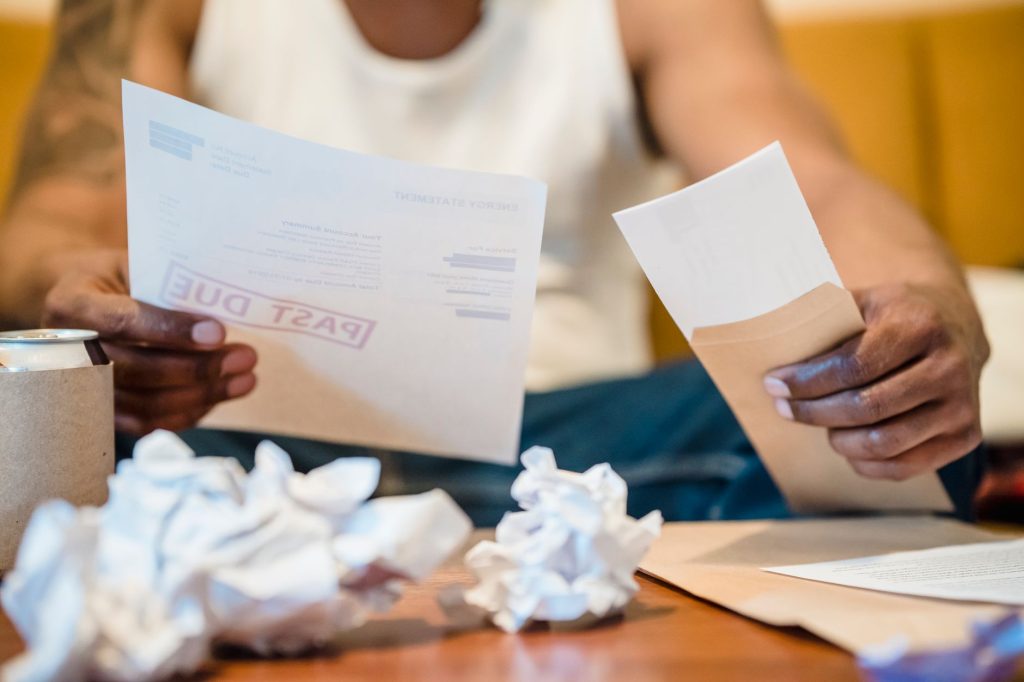
That shift matters more than people realize. When debt becomes part of your self image, shame takes over the driver’s seat. Shame is expensive. It makes people avoid unopened mail, ignore account alerts, and wait too long to ask questions. It can even keep someone from exploring options like divorce debt relief when a major life change has reshaped the entire household budget. Once debt stops being treated like a character flaw, it becomes easier to face it like any other problem that needs a plan.
The strange thing about money trouble is that it often creates silence at exactly the moment when information would help most. A person with a broken arm usually does not hide it for six months because they feel embarrassed. A person with debt might. That does not happen because debt is mathematically impossible. It happens because debt carries social meaning. People think owing money says something final about discipline, intelligence, or worth. It does not.
Debt is data, not destiny
At its core, debt is just information. There is a balance, an interest rate, a due date, and a set of terms. Some debts came from ordinary life. Some came from emergencies. Some came from a divorce, a job loss, medical bills, helping family, or trying to stay afloat during a season that simply cost more than expected. None of that turns a person into “a debt person.” It means the numbers on the page need attention.
Looking at debt this way can reduce panic. Panic says everything is ruined. Data says, “Let’s sort this.” One balance may need immediate action. Another may be negotiable. A third may be manageable with smaller monthly payments. The Consumer Financial Protection Bureau explains that if you cannot pay your credit card bills, acting quickly and contacting the card company can help, and nonprofit credit counseling may also be worth considering. That is practical advice, not moral judgment.
Why shame keeps people stuck
Shame loves vagueness. It says, “It is all bad,” without telling you what “all” means. That is why one of the most powerful things you can do is make debt visible on purpose. Write down every balance, minimum payment, interest rate, and due date. Not because you need to punish yourself, but because clarity creates choices.
This is where people often discover that their fear was both valid and exaggerated. Valid, because debt creates real pressure. Exaggerated, because the mind tends to turn five separate accounts into one giant emotional cloud. Once the cloud becomes a list, you can rank priorities, make calls, ask for hardship options, and decide where your energy will do the most good.
If collection calls are part of the picture, it also helps to remember that you still have rights. The Federal Trade Commission explains that debt collectors cannot use abusive, unfair, or deceptive practices, and they must provide validation information about the debt. Knowing that can change the emotional tone from helplessness to informed caution. See the FTC’s debt collection FAQs.
A plan works better than self criticism
Self criticism feels active, but it is often just emotional busywork. It burns energy without solving the problem. A plan, even a small one, does the opposite. It restores traction.
Start with triage. Which bills affect housing, transportation, utilities, or insurance? Which accounts are current? Which are behind? Which creditors might be willing to work with you if you call before missing another payment? The CFPB notes that many credit counseling organizations are nonprofits and may help with budgeting and debt management plans. If you want a grounded starting point for that process, review the CFPB’s overview of credit counseling.
Notice what this approach does not include. It does not require pretending everything is fine. It does not require becoming perfectly organized overnight. It does not require turning your life into a financial transformation montage. It only requires the next honest step.
Your story is bigger than your balance
One reason debt feels identity level is that it spills into so many parts of life. It affects sleep, relationships, confidence, and future plans. That emotional spillover is real. But real does not mean permanent. A hard season with money is still a season.
People rebuild from debt all the time, not because they suddenly become different humans, but because they stop confusing circumstance with selfhood. They learn the terms, make the calls, ask the questions, and keep going. Some months the progress is dramatic. Some months it is almost boring. Both count.
There is relief in admitting that debt is not a dark secret revealing who you truly are. It is a condition that can be assessed, managed, and changed over time. You are still you while the numbers are messy. You are still you while the plan is unfinished. And you are still you while learning how to handle money in a more sustainable way.
The goal is not perfection
The real goal is not to become flawless with money. It is to become less afraid of looking directly at what is true. That is where momentum begins. A missed payment is not an identity. A high balance is not a personality trait. A financial setback is not a final verdict.
Debt is a situation. Situations can improve. They can be negotiated, reorganized, reduced, and eventually resolved. The moment you stop wearing debt like a label and start treating it like a problem to work, you begin to get some power back. And that, more than any number on a statement, is what changes everything.